2026 Equalization Report
Equalization Department Letter
Grand Traverse County
Governmental Center
400 Boardman Ave
Traverse City, MI 49684
The Grand Traverse County Equalization Department has prepared this equalization report as authorized by the County Board of Commissioners. I recommend that the Grand Traverse County Board of Commissioners adopt the proposed County equalized values in this report.
This report is a result of an equalization study in every class of real property and of the total personal property in all fourteen (14) assessing units of Grand Traverse County.
This report does not embrace any property taxed under P.A. 77 of 1951; P.A. 68 of 1963; P.A. 199 of 1974; P.A. 385 of 1994; P.A. 224 of 1995; P.A. 147 of 1992 or Section 5 of Article IX of the Constitution of the State of Michigan.
All County equalized values are subject to review and change by the Michigan State Tax Commission until the fourth Monday in May, when the final order is issued.
The resolution adopting the 2026 Grand Traverse County Equalization Report is located on the pages following.
Acknowledgements
In facilitating the completion of a project of this nature and magnitude, the support of a number of organizations and individuals was absolutely necessary and I am grateful to all the participants.
The burden of maintaining a county-wide property information network while meeting impending statutory deadlines was carried out extraordinarily well by the staff of the Grand Traverse County Equalization Department. I would like to thank the Grand Traverse County Board of Commissioners for providing the Department with the resources to accomplish these duties. I would also like to express my gratitude to the Assessors of the city, townships and villages of Grand Traverse County for their prompt assistance in the assembling and reporting of data for this analysis.
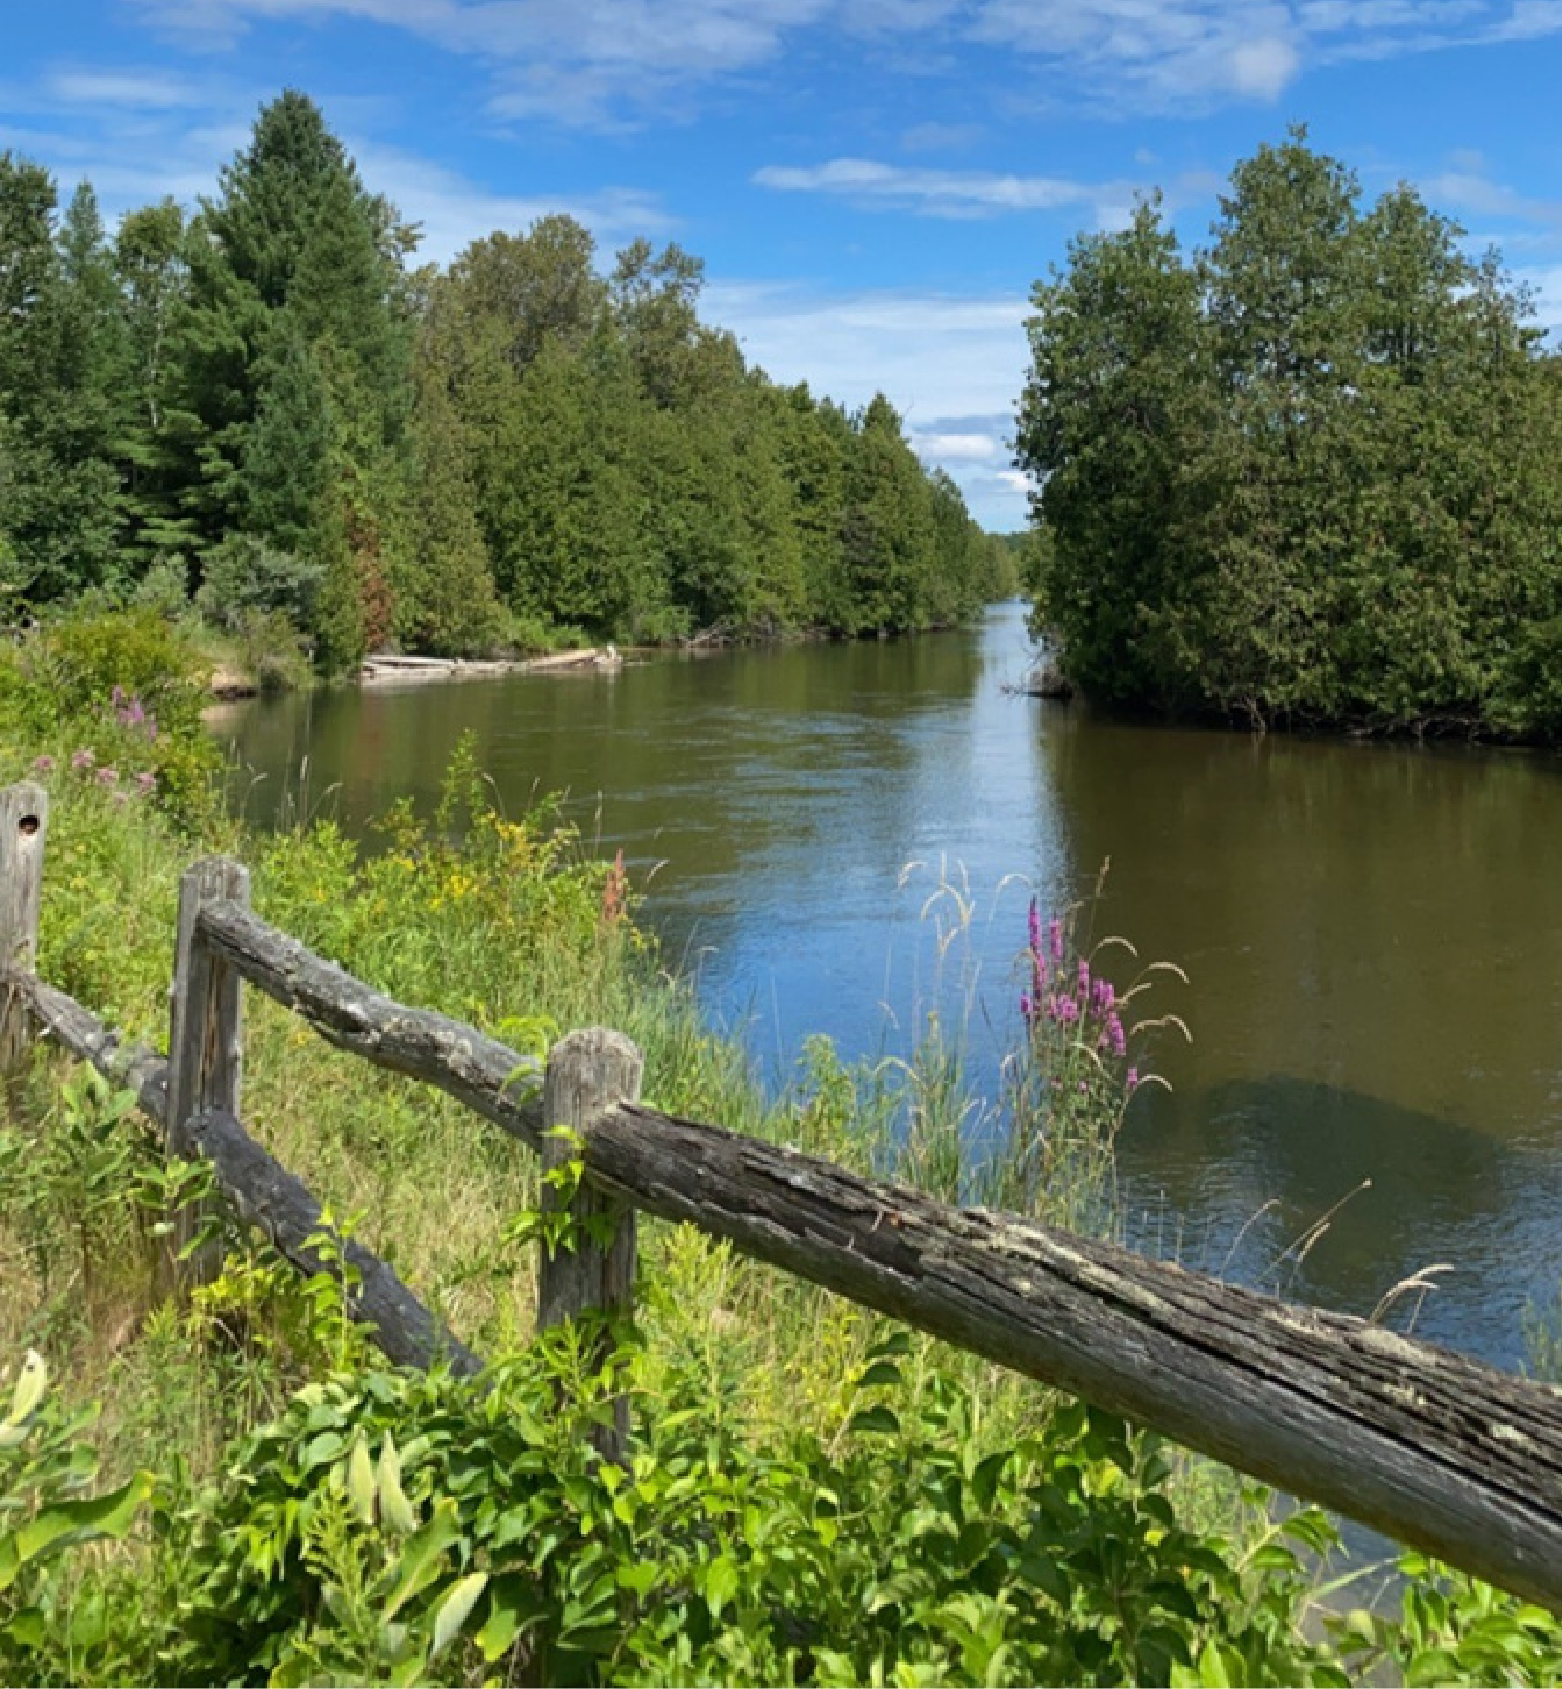
The cover of this report is a photo of The Boardman/Ottaway River taken by Hailey McGuire.
Foreword
The State Constitution commands the legislature to establish a system of property taxation and of equalization of assessments. The rationale underlying this approach is that the cost of municipal services, such as police, fire protection and education should be borne through taxation imposed upon the general public. That taxation is required to be uniform and fair to all taxpayers; County Equalization is required to ensure that.
Grand Traverse County Equalization Department
Reports To
Board of Commissioners
- Scott Sieffert – Chair
- TJ Andrews – Vice-Chair
- Lauren Flynn
- Rob Hentschel
- Brian McAllister
- Penny Morris
- Darryl Nelson
- Fern Spence
- Ashlea Walter
Management Team
- Administrator Nate Alger
- Deputy Administrator Christopher Forsyth
Department of Equalization/GIS
- James D. Baker – Equalization Director, MMAO (4)
- Darren Darge – Deputy Equalization Director, MAAO (3)
- Hailey McGuire – Appraiser, MCAT
- Nicholas Myers – Appraiser, MCAT
- Joshua Green – Deputy GIS Director, GISP
- Mike Barres - GIS Analyst, MAAO (3)
- Dariusz Szjaner – GIS Technician
Supervisors, Assessors, Presidents, & Managers
Grand Traverse County 2025
| Local Unit | Supervisor | Assessor |
|---|---|---|
| Acme Township (01) | Doug White | Dawn Kuhns |
| Blair Township (02) | Nicole Blonshine | Wendy Witkop |
| East Bay Township (03) | Beth Friend | Ryan Porte |
| Fife Lake Township (04) | Lisa Radtke | Jessica Plude |
| Garfield Charter Township (05) | Joe McManus | Polly Cairns |
| Grant Township (06) | Crystal Breithaupt | Isaac Entz |
| Green Lake Township (07) | Marvin D. Radtke, Jr. | William Muha |
| Long Lake Township (08) | Ron Lemcool | Angela Friske |
| Mayfield Township (09) | John Ockert | David Brown |
| Paradise Township (10) | Rob Lajko | Dawn Kuhns |
| Peninsula Township (11) | Maura Sanders | Sally Murray |
| Union Township (12) | Doug Mansfield | Debra Johnson |
| Whitewater Township (13) | Linda Slopsema | Dawn Kuhns |
| President | ||
|---|---|---|
| Fife Lake Village (41) | Tawni Deike | Jessica Plude |
| Manager | ||
|---|---|---|
| Kingsley Village (42) | Charlie Jetter | Dawn Kuhns |
| City of Traverse City (51) | Benjamin Marentette | Amy Robbins |
2026 GRAND TRAVERSE COUNTY - REAL PROPERTY
| TOWNSHIPS & CITY |
Parcel Count 2025 |
Parcel Count 2026 |
Parcel Count % Change |
CEV 2025 | CEV 2026 | County Equalized % Change |
TAXABLE 2025 | TAXABLE 2026 | Taxable % Change |
|---|---|---|---|---|---|---|---|---|---|
| Acme | 3,387 | 3,394 | 0.21% | $854,803,800 | $955,699,900 | 11.80% | $524,020,803 | $576,950,492 | 10.10% |
| Blair | 4,908 | 5,016 | 2.20% | $730,737,400 | $798,024,590 | 9.21% | $484,493,726 | $534,954,467 | 10.42% |
| East Bay | 7,958 | 8,061 | 1.29% | $1,417,662,300 | $1,534,793,900 | 8.26% | $871,906,727 | $939,843,369 | 7.79% |
| Fife Lake | 1,286 | 1,289 | 0.23% | $156,955,900 | $174,076,860 | 10.91% | $85,041,705 | $90,869,423 | 6.85% |
| Garfield | 8,182 | 8,673 | 6.00% | $1,986,134,800 | $2,055,683,968 | 3.50% | $1,341,048,394 | $1,397,535,100 | 4.21% |
| Grant | 1,070 | 1,077 | 0.65% | $127,036,500 | $139,624,500 | 9.91% | $74,755,850 | $81,054,567 | 8.43% |
| Green Lake | 3,979 | 4,079 | 2.51% | $728,513,400 | $783,205,000 | 7.51% | $433,307,610 | $462,902,843 | 6.83% |
| Long Lake | 5,160 | 5,228 | 1.32% | $1,318,829,900 | $1,419,819,300 | 7.66% | $787,049,222 | $839,859,626 | 6.71% |
| Mayfield | 1,177 | 1,190 | 1.10% | $149,831,200 | $161,672,900 | 7.90% | $92,589,199 | $99,247,377 | 7.19% |
| Paradise | 2,667 | 2,676 | 0.34% | $327,914,700 | $358,788,400 | 9.42% | $206,803,209 | $223,297,117 | 7.98% |
| Peninsula | 4,304 | 4,218 | -2.00% | $1,937,186,700 | $2,072,135,600 | 6.97% | $1,100,265,141 | $1,184,507,965 | 7.66% |
| Union | 418 | 426 | 1.91% | $67,114,000 | $72,613,000 | 8.19% | $39,031,250 | $41,841,056 | 7.20% |
| Whitewater | 2,000 | 2,014 | 0.70% | $558,441,800 | $588,840,100 | 5.44% | $311,027,746 | $332,938,653 | 7.04% |
| Traverse City | 8,007 | 8,065 | 0.72% | $2,350,349,700 | $2,469,436,300 | 5.07% | $1,527,948,700 | $1,600,544,697 | 4.75% |
| TOTALS | 54,503 | 55,406 | 1.66% | $12,711,512,100 | $13,584,414,318 | 6.87% | $7,879,289,282 | $8,406,346,752 | 6.69% |
2026 GRAND TRAVERSE COUNTY - PERSONAL PROPERTY
| TOWNSHIPS & CITY |
Parcel Count 2025 |
Parcel Count 2026 |
Parcel Count % Change |
CEV 2025 | CEV 2026 | County Equalized % Change |
TAXABLE 2025 | TAXABLE 2026 | Taxable % Change |
|---|---|---|---|---|---|---|---|---|---|
| Acme | 162 | 160 | -1.23% | $29,404,300 | $29,621,100 | 0.74% | $29,404,300 | $29,621,100 | 0.74% |
| Blair | 455 | 435 | -4.40% | $38,982,600 | $40,247,500 | 3.24% | $38,982,600 | $40,247,500 | 3.24% |
| East Bay | 451 | 454 | 0.67% | $32,732,300 | $33,927,000 | 3.65% | $32,732,300 | $33,927,000 | 3.65% |
| Fife Lake | 53 | 52 | -1.89% | $3,144,277 | $3,116,200 | -0.89% | $3,144,277 | $3,116,200 | -0.89% |
| Garfield | 1,633 | 1,601 | -1.96% | $116,597,300 | $120,753,200 | 3.56% | $116,597,300 | $120,753,200 | 3.56% |
| Grant | 49 | 46 | -6.12% | $6,474,000 | $6,383,400 | -1.40% | $6,474,000 | $6,383,400 | -1.40% |
| Green Lake | 182 | 182 | 0.00% | $21,632,100 | $21,850,400 | 1.01% | $21,632,100 | $21,850,400 | 1.01% |
| Long Lake | 208 | 214 | 2.88% | $12,828,000 | $14,510,600 | 13.12% | $12,828,000 | $14,510,600 | 13.12% |
| Mayfield | 71 | 71 | 0.00% | $5,616,000 | $5,765,700 | 2.67% | $5,616,000 | $5,765,700 | 2.67% |
| Paradise | 87 | 88 | 1.15% | $15,877,100 | $15,679,700 | -1.24% | $15,877,100 | $15,679,700 | -1.24% |
| Peninsula | 117 | 115 | -1.71% | $16,444,500 | $18,316,100 | 11.38% | $16,444,500 | $18,316,100 | 11.38% |
| Union | 38 | 37 | -2.63% | $1,969,300 | $2,011,400 | 2.14% | $1,969,300 | $2,011,400 | 2.14% |
| Whitewater | 86 | 87 | 1.16% | $11,078,900 | $12,310,300 | 11.11% | $11,078,900 | $12,310,300 | 11.11% |
| Traverse City | 1,775 | 1,773 | -0.11% | $52,014,300 | $52,533,100 | 1.00% | $52,014,300 | $52,533,100 | 1.00% |
| TOTALS | 5,367 | 5,315 | -0.97% | $364,794,977 | $377,025,700 | 3.35% | $364,795,277 | $377,025,700 | 3.35% |
2026 GRAND TRAVERSE COUNTY - ALL AD VALOREM PROPERTY
| TOWNSHIPS & CITY |
Parcel Count 2025 |
Parcel Count 2026 |
Parcel Count % Change |
CEV 2025 | CEV 2026 | County Equalized % Change |
TAXABLE 2025 | TAXABLE 2026 | Taxable % Change |
|---|---|---|---|---|---|---|---|---|---|
| Acme | 3,549 | 3,554 | 0.14% | $884,208,100 | $985,321,000 | 11.44% | $553,425,103 | $606,571,592 | 9.60% |
| Blair | 5,363 | 5,451 | 1.64% | $769,720,000 | $838,272,090 | 8.91% | $523,476,326 | $575,201,967 | 9.88% |
| East Bay | 8,409 | 8,515 | 1.26% | $1,450,394,600 | $1,568,720,900 | 8.16% | $904,639,027 | $973,770,369 | 7.64% |
| Fife Lake | 1,339 | 1,341 | 0.15% | $160,100,177 | $177,193,060 | 10.68% | $88,185,982 | $93,985,623 | 6.58% |
| Garfield | 9,815 | 10,274 | 4.68% | $2,102,732,100 | $2,176,437,168 | 3.51% | $1,457,645,694 | $1,518,288,300 | 4.16% |
| Grant | 1,119 | 1,123 | 0.36% | $133,510,500 | $146,007,900 | 9.36% | $81,229,850 | $87,437,967 | 7.64% |
| Green Lake | 4,161 | 4,261 | 2.40% | $750,145,500 | $805,055,400 | 7.32% | $454,939,710 | $484,753,243 | 6.55% |
| Long Lake | 5,368 | 5,442 | 1.38% | $1,331,657,900 | $1,434,329,900 | 7.71% | $799,877,222 | $854,370,226 | 6.81% |
| Mayfield | 1,248 | 1,261 | 1.04% | $155,447,200 | $167,438,600 | 7.71% | $98,205,199 | $105,013,077 | 6.93% |
| Paradise | 2,754 | 2,764 | 0.36% | $343,791,800 | $374,468,100 | 8.92% | $222,680,309 | $238,976,817 | 7.32% |
| Peninsula | 4,421 | 4,333 | -1.99% | $1,953,631,200 | $2,090,451,700 | 7.00% | $1,116,709,641 | $1,202,824,065 | 7.71% |
| Union | 456 | 463 | 1.54% | $69,083,300 | $74,624,400 | 8.02% | $41,000,550 | $43,852,456 | 6.96% |
| Whitewater | 2,086 | 2,101 | 0.72% | $569,520,700 | $601,150,400 | 5.55% | $322,106,646 | $345,248,953 | 7.18% |
| Traverse City | 9,782 | 9,838 | 0.57% | $2,402,364,000 | $2,521,969,400 | 4.98% | $1,579,963,300 | $1,653,077,797 | 4.63% |
| TOTALS | 59,870 | 60,721 | 1.42% | $13,076,307,077 | $13,961,440,018 | 6.77% | $8,244,084,559 | $8,783,372,452 | 6.54% |
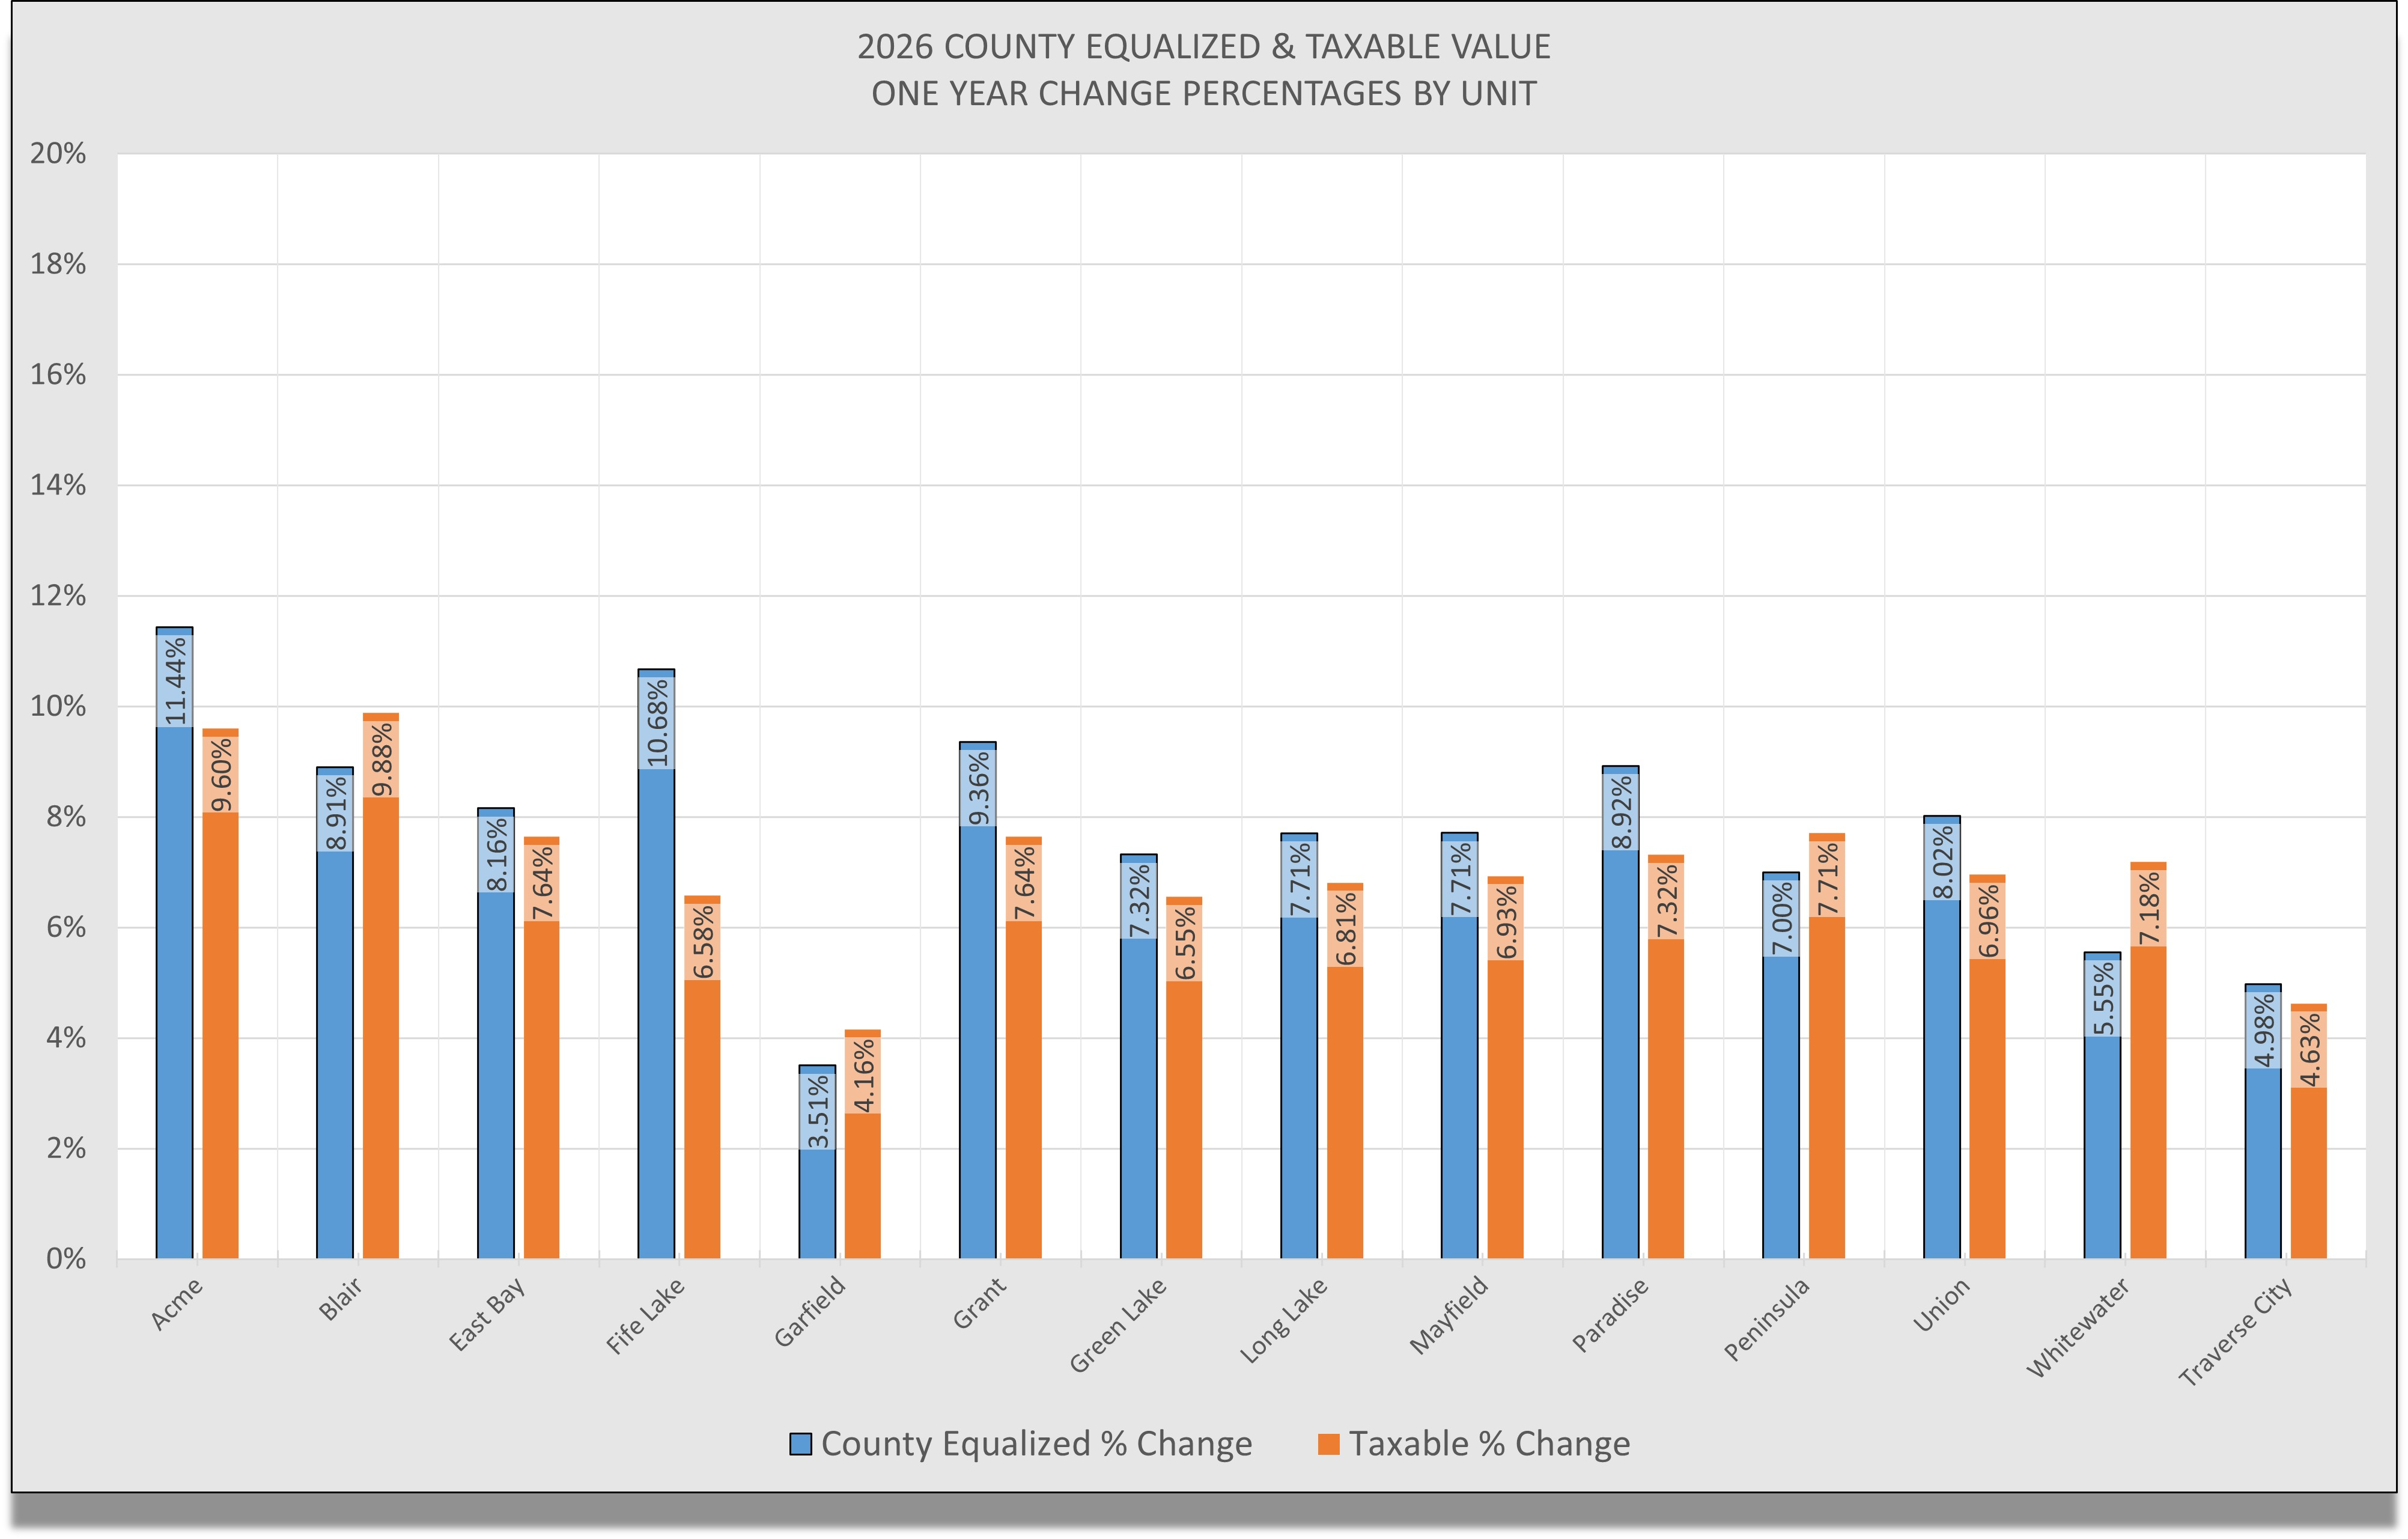
2026 County Equalized & Taxable Value - One Year Change Percentages by Unit
Accessible view
2026 County Equalized & Taxable Value: One Year Change Percentages by Unit
Comparison of one-year percentage changes in County Equalized Value versus Taxable Value across local units.
| Unit | County Equalized % Change | Taxable % Change |
|---|---|---|
| Acme | 11.44% | 9.60% |
| Blair | 8.91% | 9.88% |
| East Bay | 8.16% | 7.64% |
| Fife Lake | 10.68% | 6.58% |
| Garfield | 3.51% | 4.16% |
| Grant | 9.36% | 7.64% |
| Green Lake | 7.32% | 6.55% |
| Long Lake | 7.71% | 6.81% |
| Mayfield | 7.71% | 6.93% |
| Paradise | 8.92% | 7.32% |
| Peninsula | 7.00% | 7.71% |
| Union | 8.02% | 6.96% |
| Whitewater | 5.55% | 7.18% |
| Traverse City | 4.98% | 4.63% |
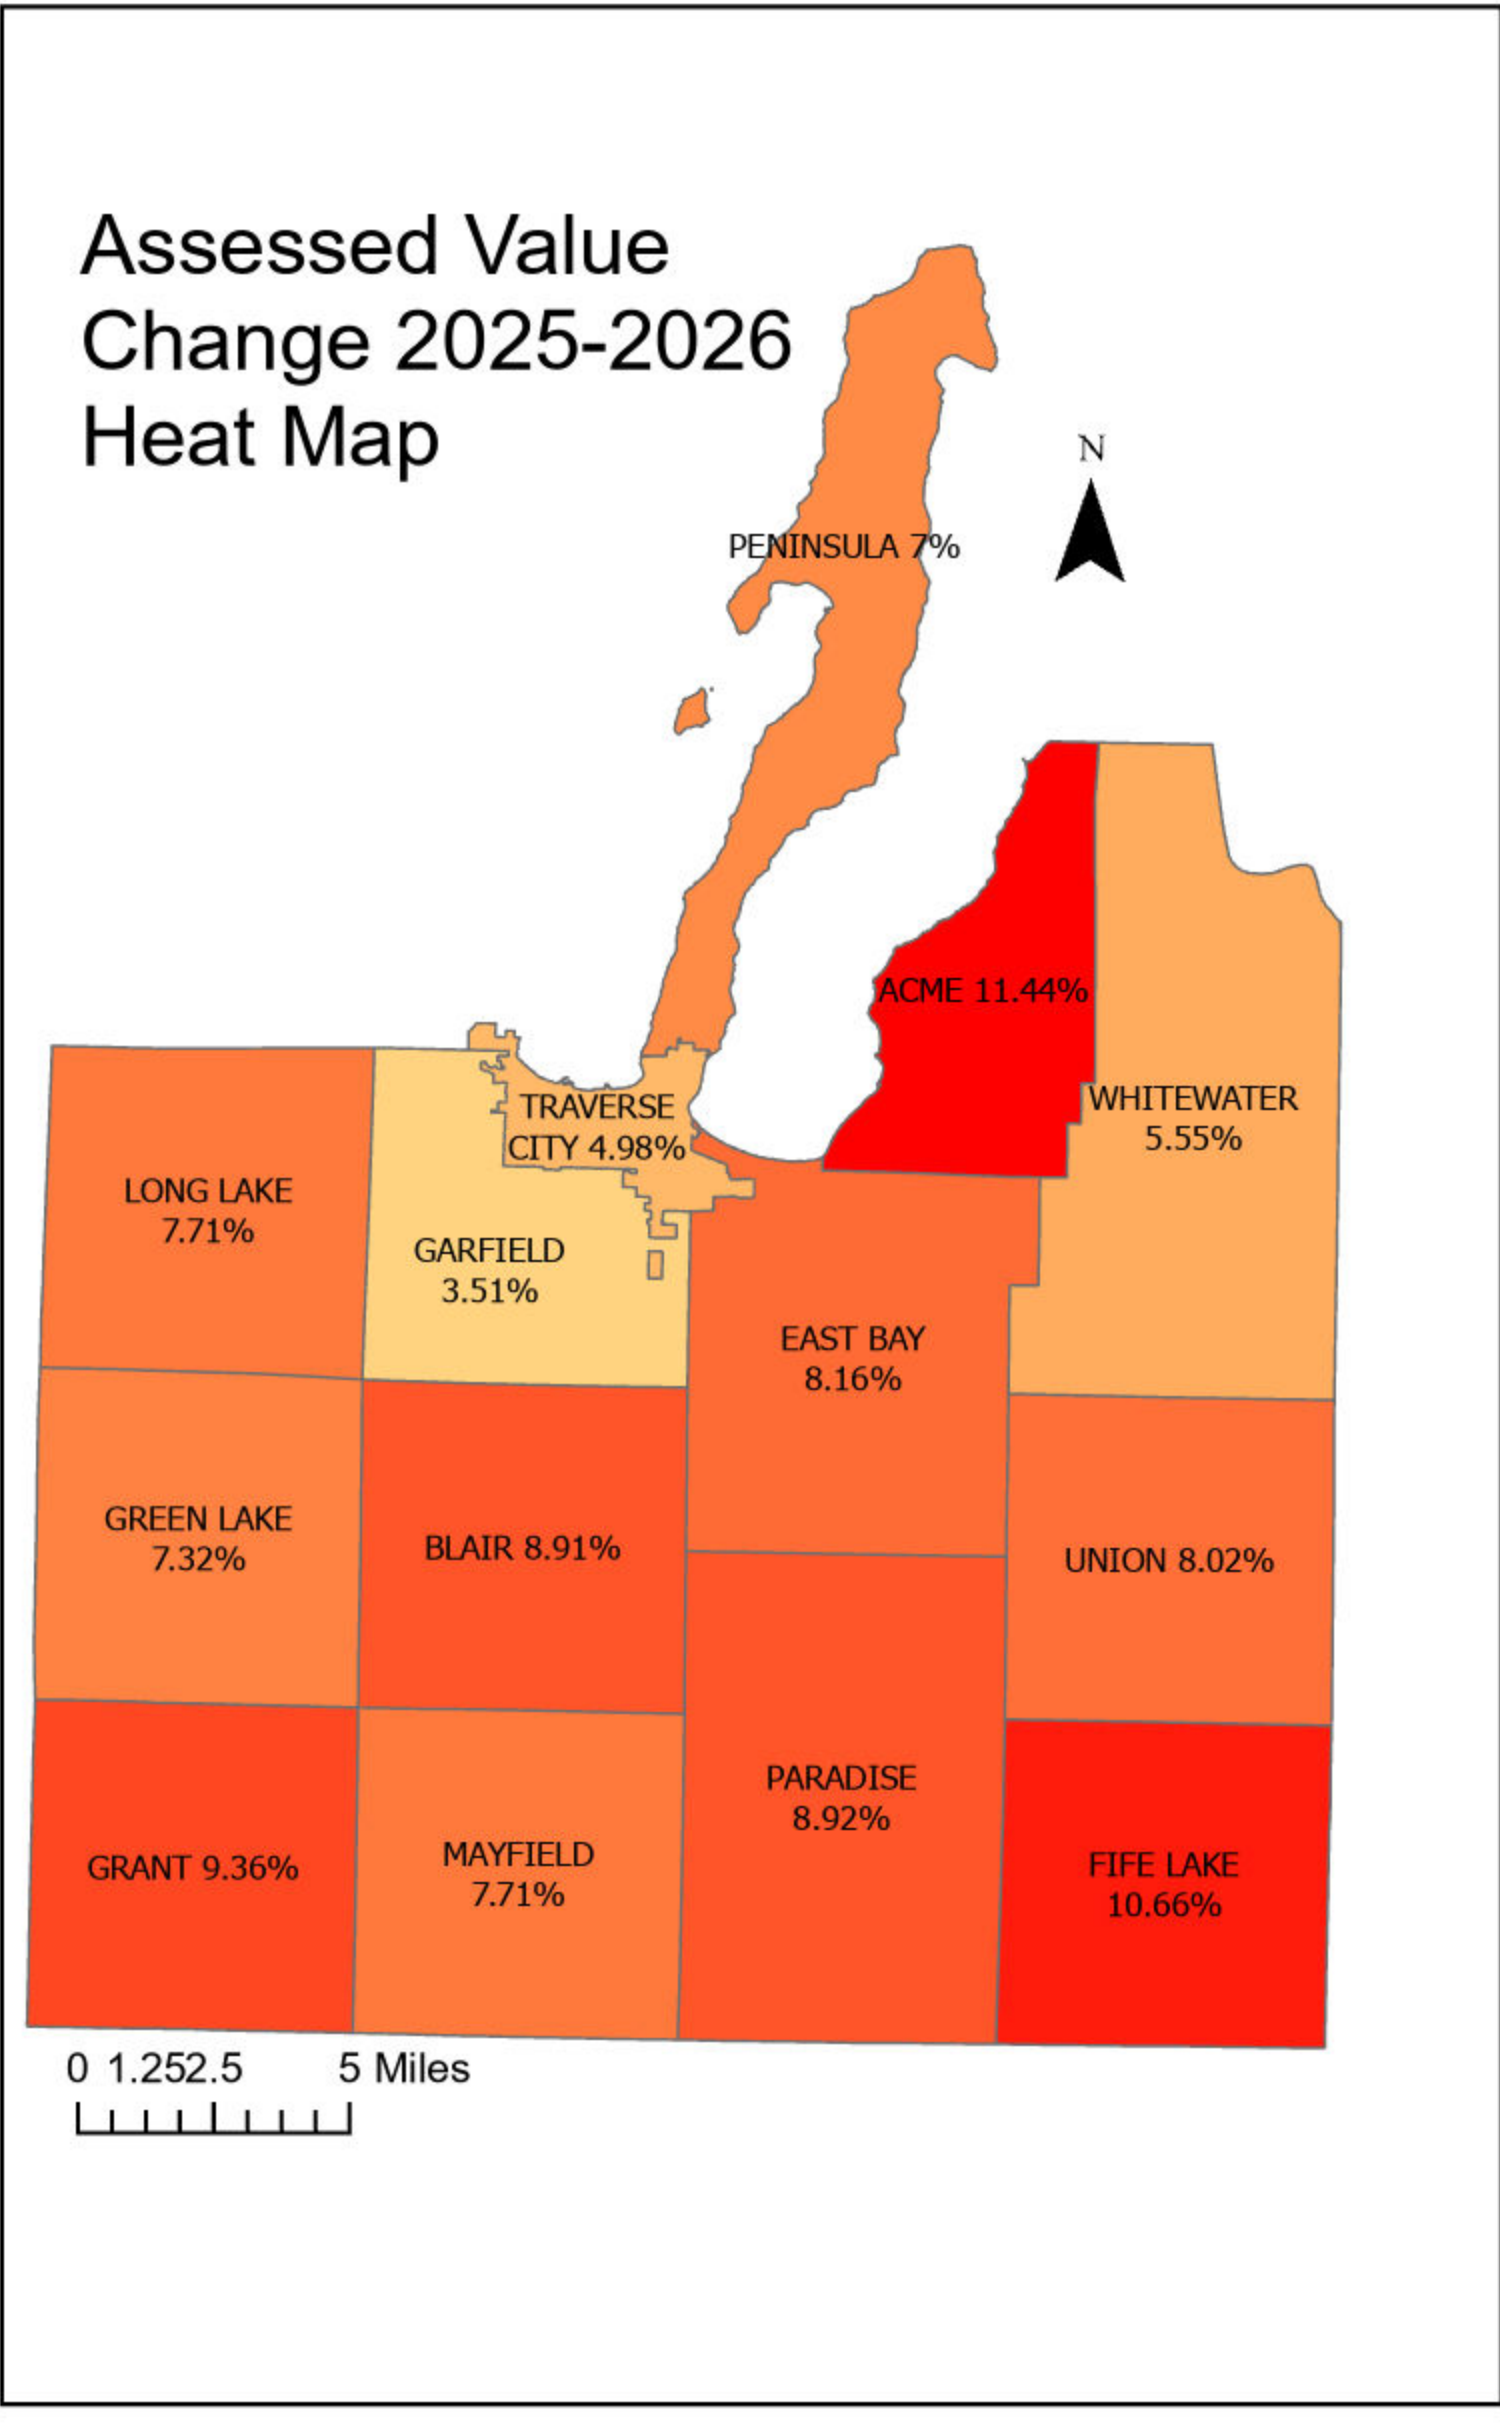
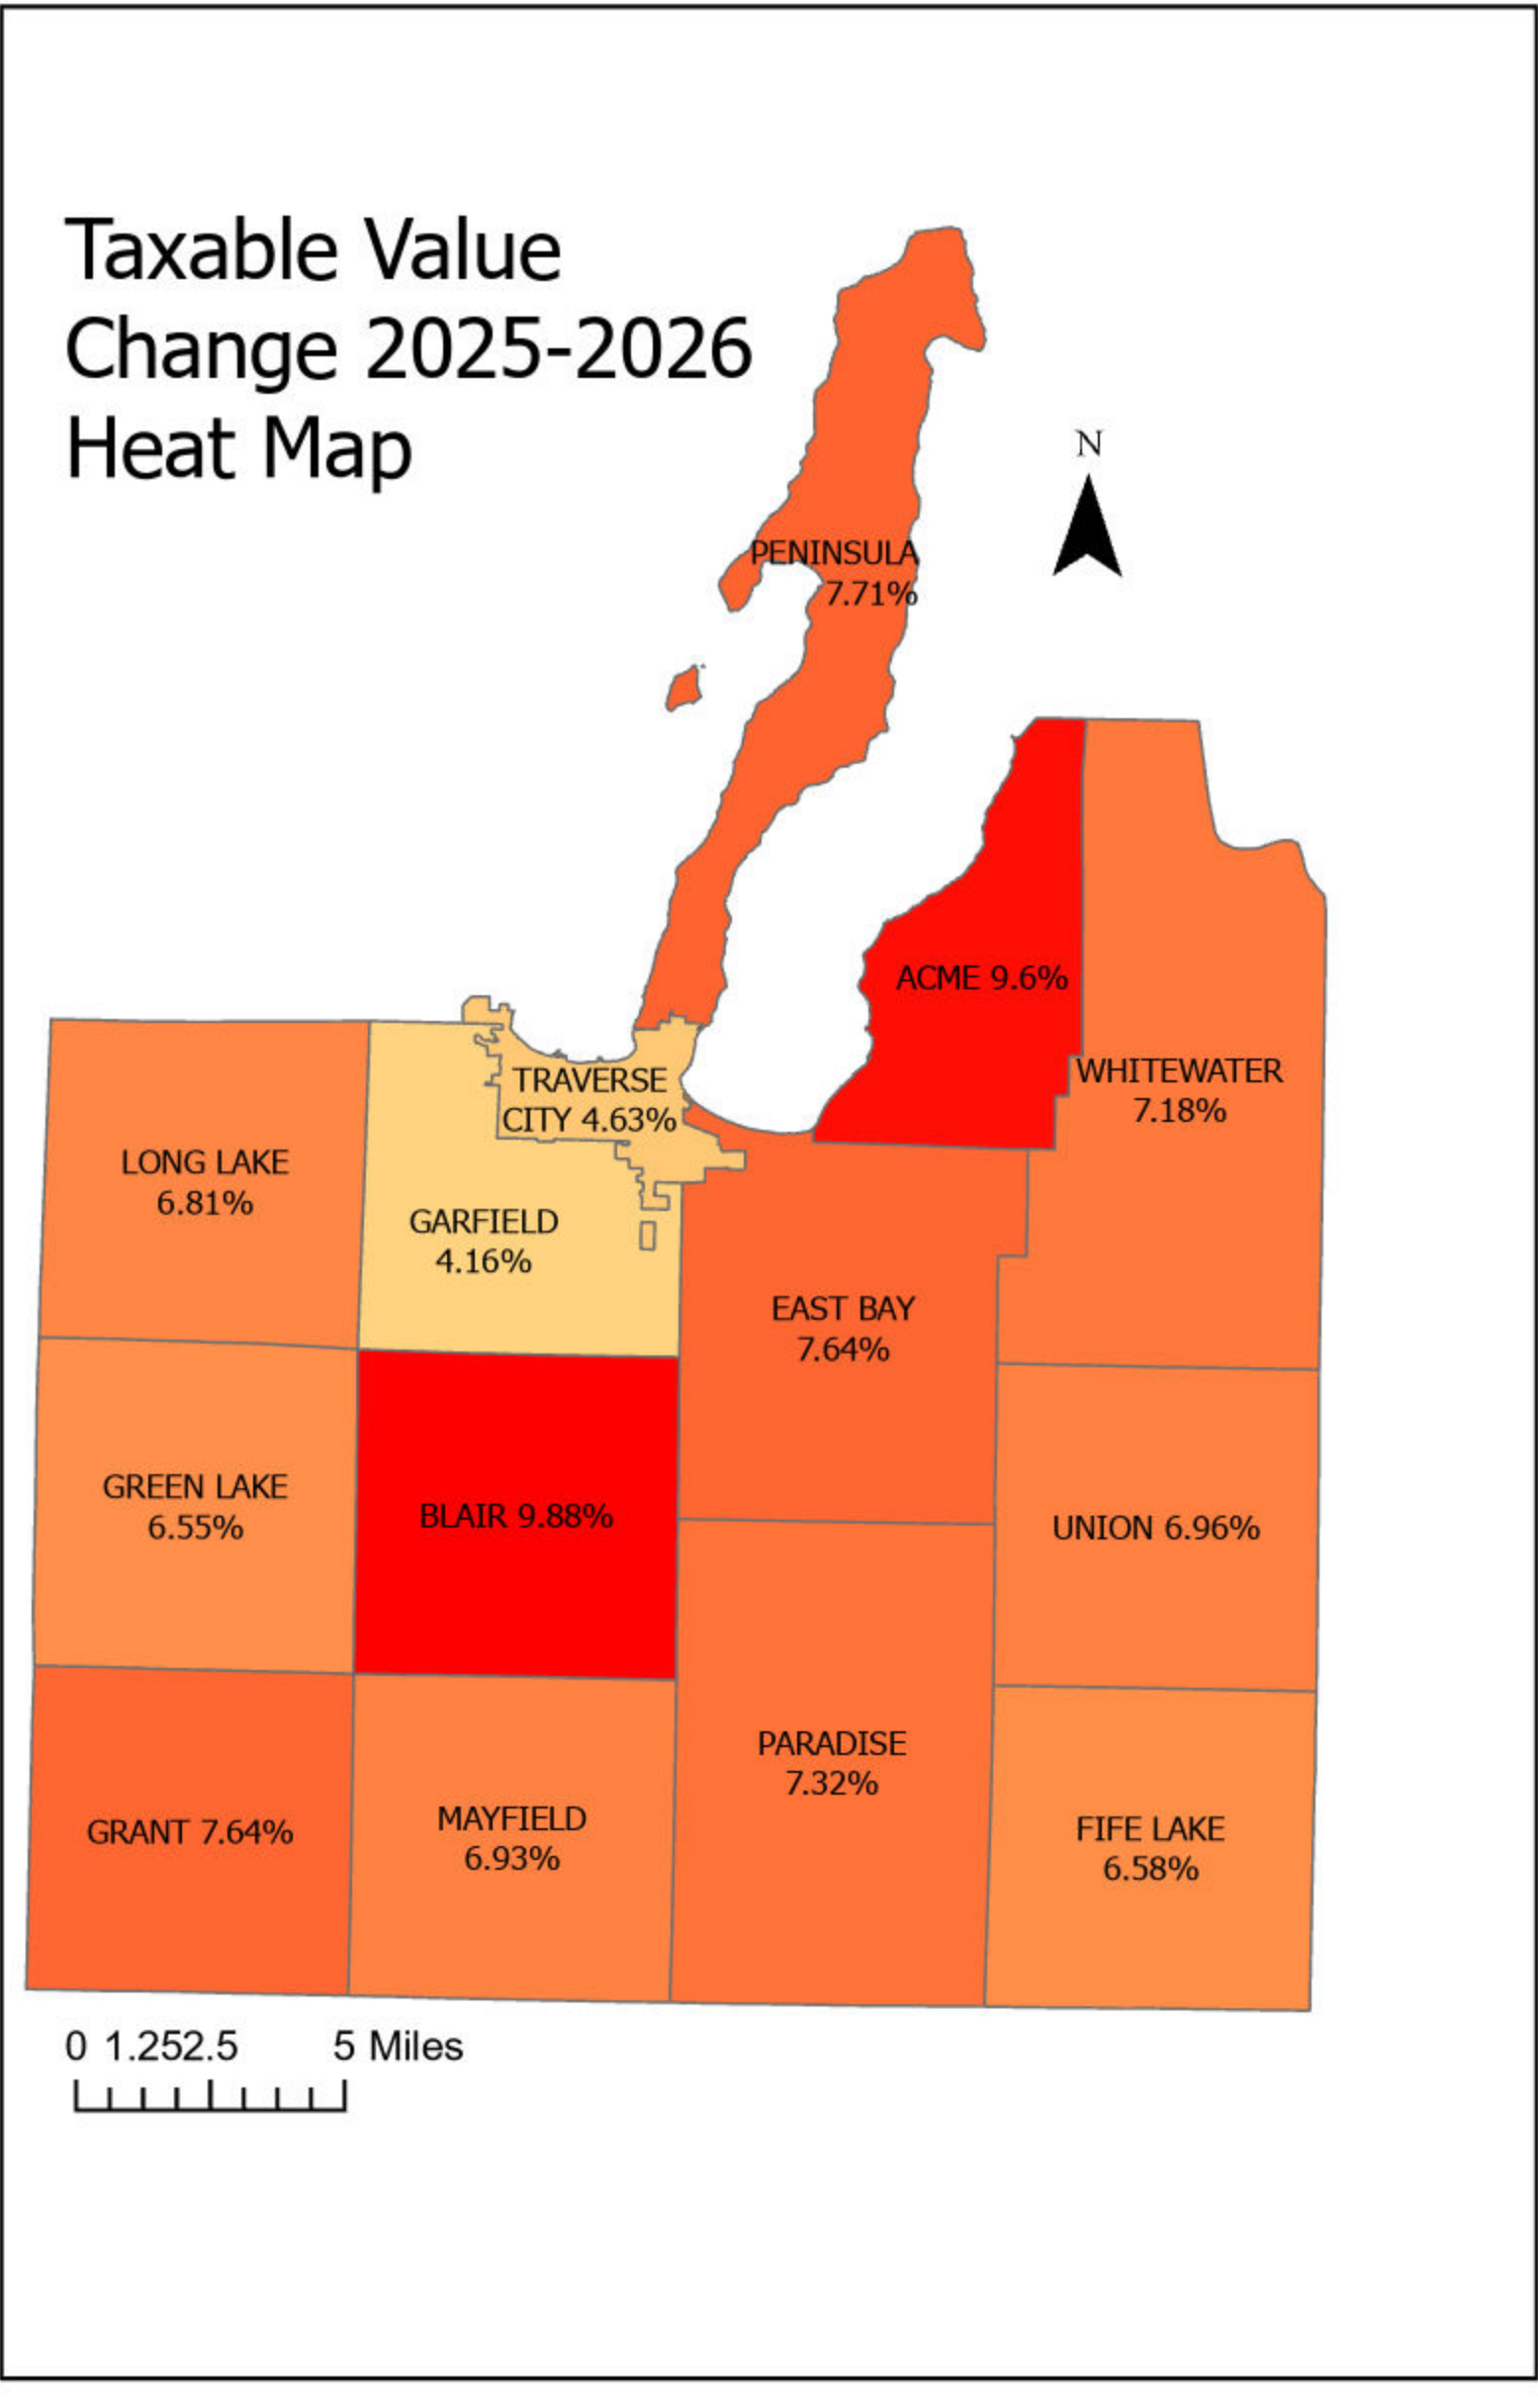
Grand Traverse County Property Value Changes (2025–2026)
Comparative Heat Maps: Assessed Value vs. Taxable Value
Accessible view
Overview: The maps illustrate projected percentage changes in Assessed Value and Taxable Value for 2025–2026 across municipalities in Grand Traverse County, Michigan. Colors range from pale yellow-orange (lower increases) to deep red (higher increases).
| Municipality | Assessed Value Change (%) | Taxable Value Change (%) |
|---|---|---|
| Acme | 11.44% | 9.60% |
| Blair | 8.91% | 9.88% |
| East Bay | 8.16% | 7.64% |
| Fife Lake | 10.66% | 6.58% |
| Garfield | 3.51% | 4.16% |
| Grant | 9.36% | 7.64% |
| Green Lake | 7.32% | 6.55% |
| Long Lake | 7.71% | 6.81% |
| Mayfield | 7.71% | 6.93% |
| Paradise | 8.92% | 7.32% |
| Peninsula | 7.00% | 7.71% |
| Traverse City | 4.98% | 4.63% |
| Union | 8.02% | 6.96% |
| Whitewater | 5.55% | 7.18% |
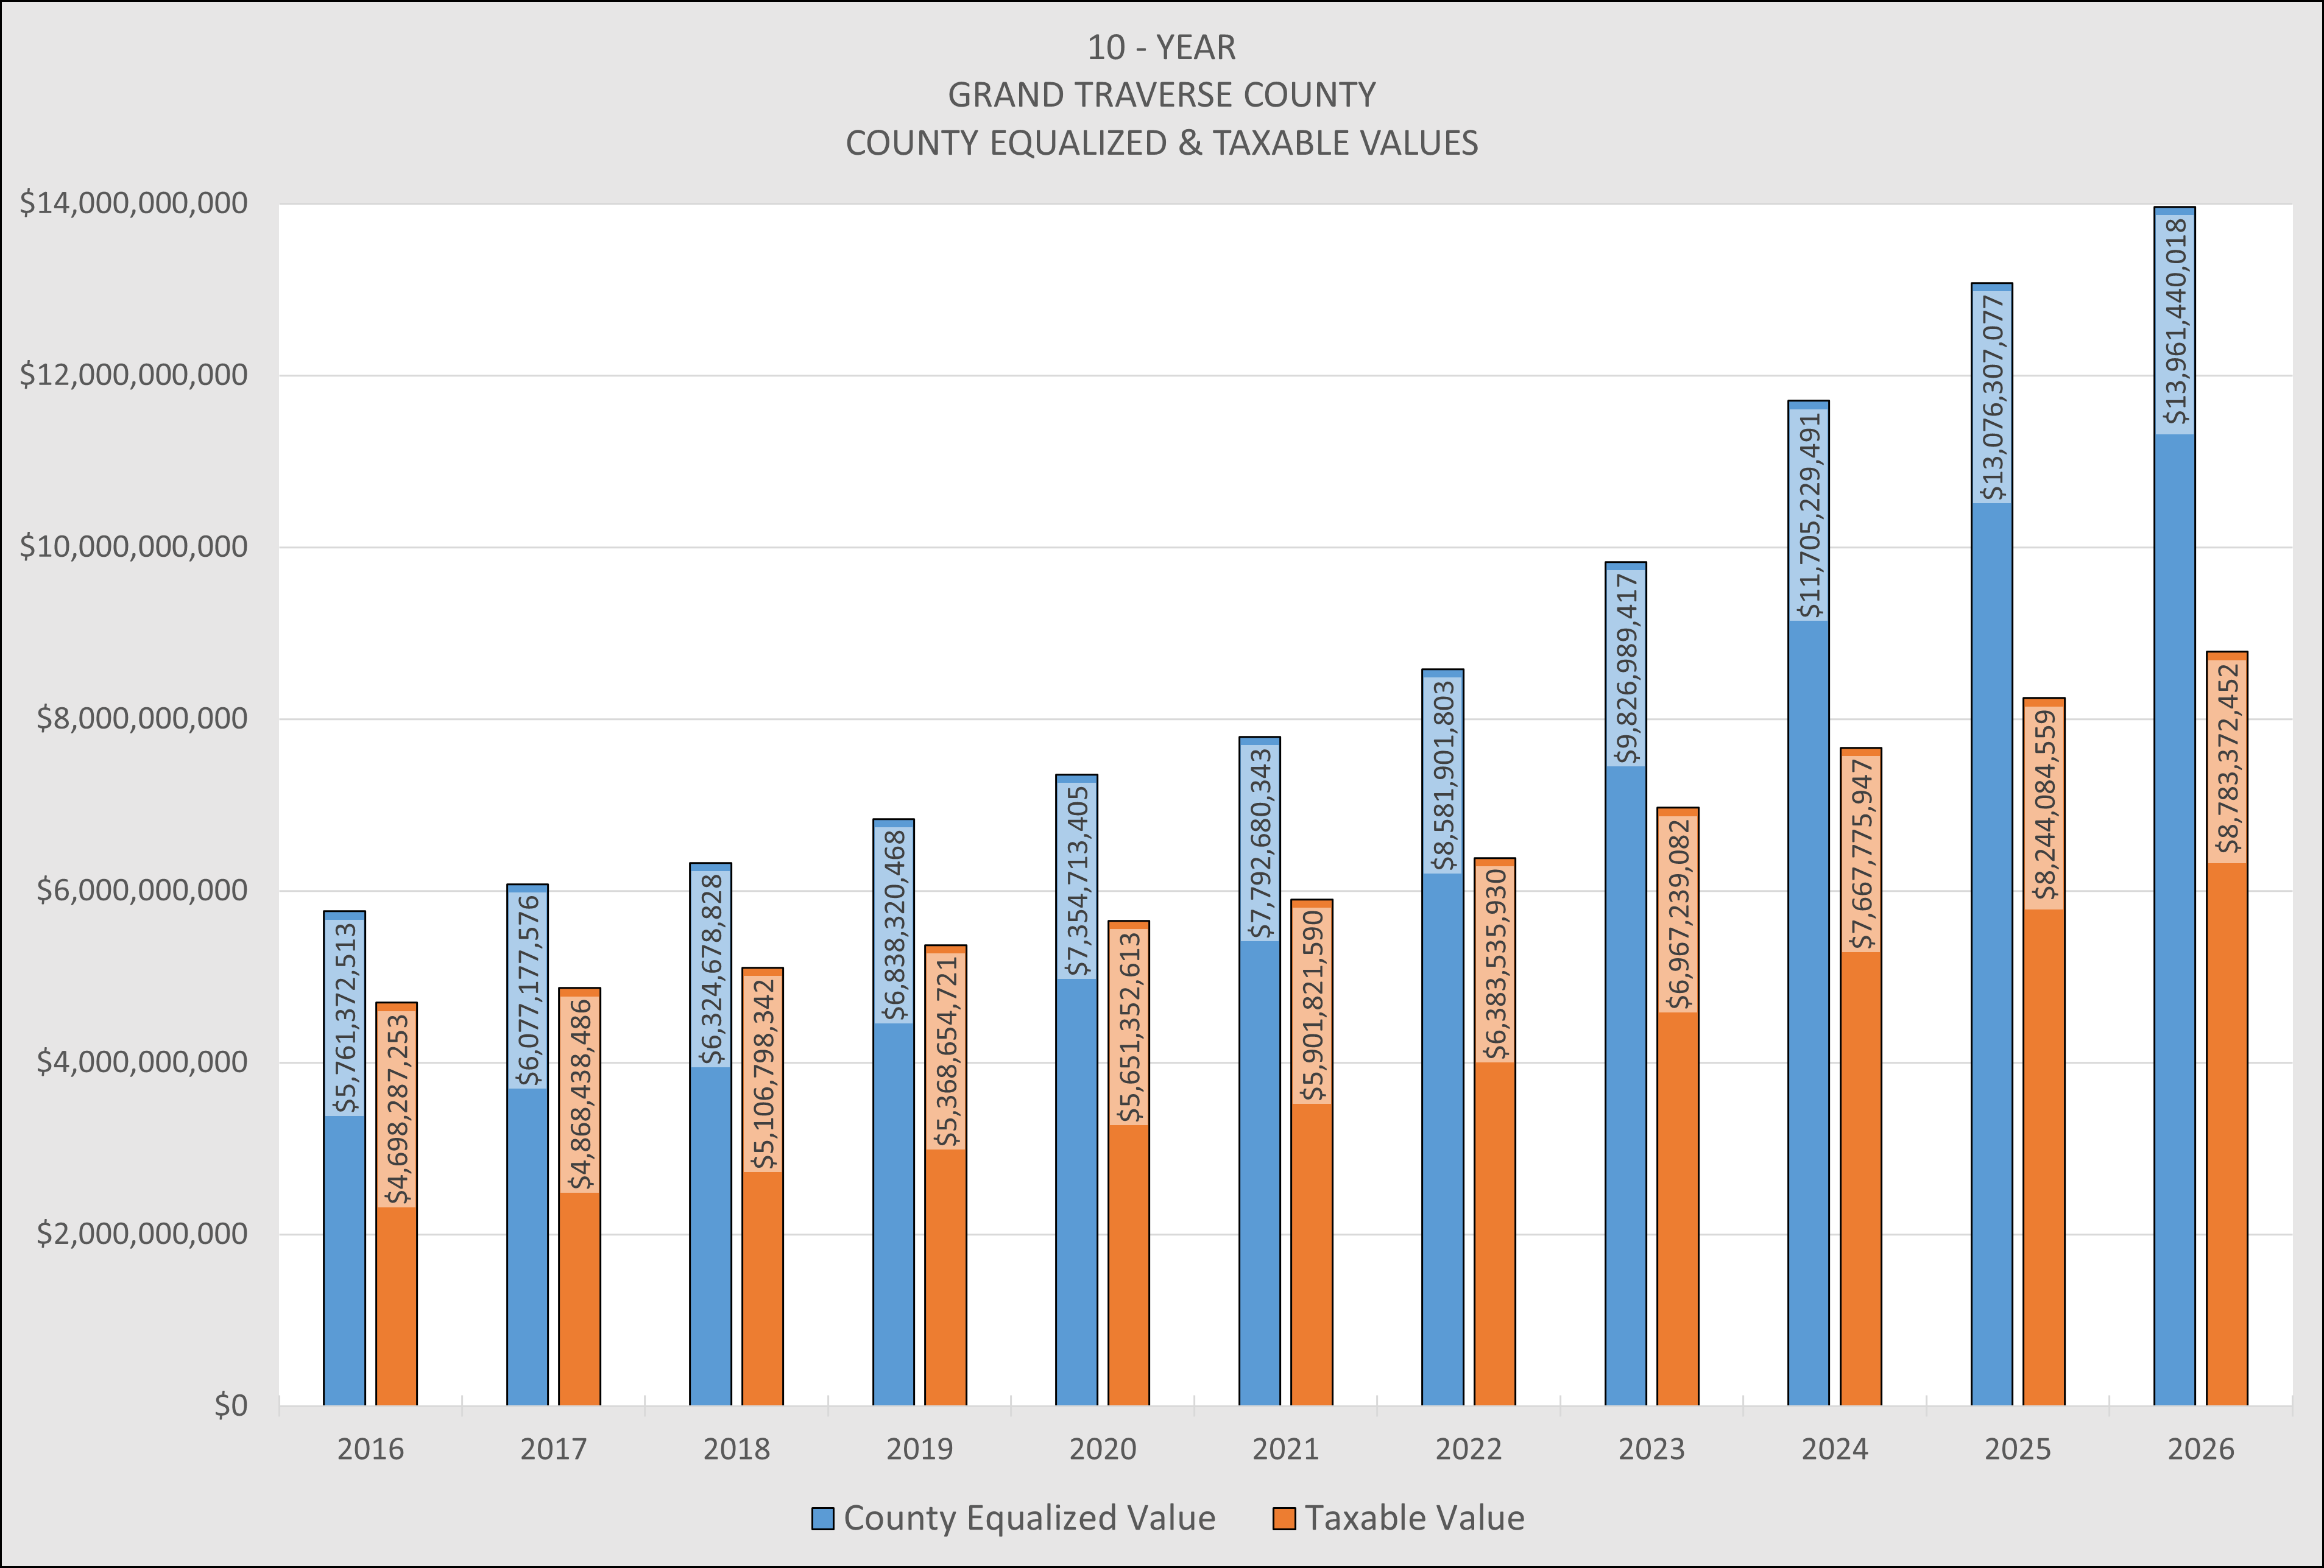
10-Year Equalized & Taxable Values
Accessible view
Grand Traverse County: 10-Year Equalized & Taxable Values (2016–2026)
Annual comparison of County Equalized Value versus Taxable Value in USD ($).
Scroll horizontally to view all columns.
| Year | County Equalized Value ($) | Taxable Value ($) |
|---|---|---|
| 2016 | $5,761,372,513 | $4,698,287,253 |
| 2017 | $6,077,177,576 | $4,868,438,486 |
| 2018 | $6,324,678,828 | $5,106,798,342 |
| 2019 | $6,838,320,468 | $5,368,654,721 |
| 2020 | $7,354,713,405 | $5,651,352,613 |
| 2021 | $7,792,680,343 | $5,901,821,590 |
| 2022 | $8,581,901,803 | $6,383,535,930 |
| 2023 | $9,826,989,417 | $6,967,239,082 |
| 2024 | $11,705,229,491 | $7,667,775,947 |
| 2025 | $13,076,307,077 | $8,244,084,559 |
| 2026 | $13,961,440,018 | $8,783,372,452 |