Delaware County, Indiana
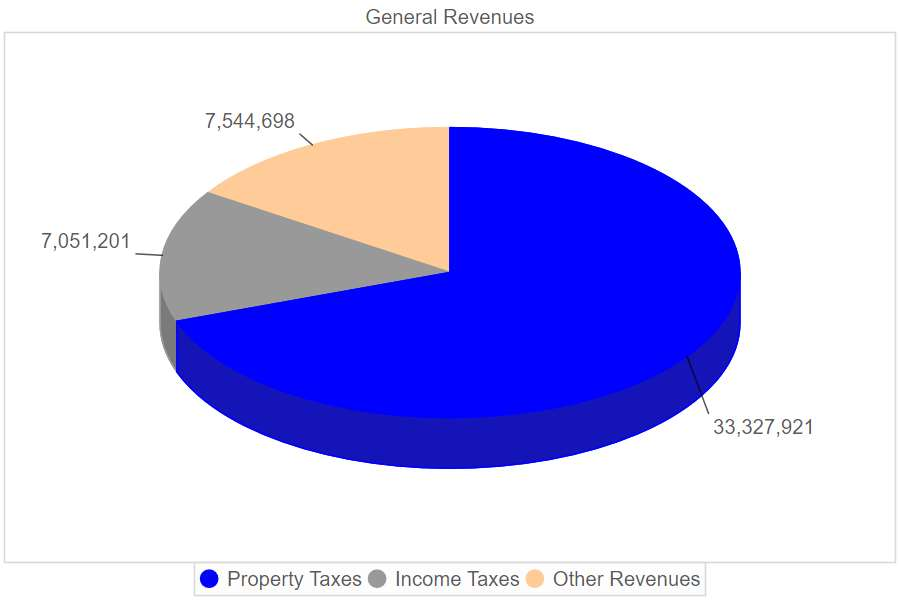
The following displays the General Revenues by source for the County's governmental activities. General revenues are used to help offset funding shortfalls related to governmental functions detailed in the preceding graph:
Accessible view
Breakdown of General Revenues by source for governmental activities:
Swipe or scroll horizontally to view all columns.
| Revenue Source | Amount ($) |
|---|---|
| Property Taxes | 33,327,921 |
| Other Revenues | 7,544,698 |
| Income Taxes | 7,051,201 |
Business-Type Activities
Business-type activities resulted in a decrease in net position of $52,045 in 2025 compared to an increase of $73,105 in 2024.
Financial Analysis of the Government's Funds
As noted earlier, the County uses fund accounting to ensure and demonstrate compliance with finance-related legal requirements.
Governmental Funds. The focus of the County's governmental funds is to provide information on near-term inflows, outflows and balances of spendable resources. Such information is useful to assess the County's financial requirements. Unassigned fund balance may serve as a useful measure of a government's net resources available for spending at the end of the fiscal year.
Fund balances are the differences between assets plus deferred outflows of resources and liabilities plus deferred inflows of resources in a governmental fund. The nonspendable fund balance includes amounts that are not in spendable form or amounts that are required to be maintained intact. Restricted fund balance includes amounts that can be spent only for the specific purposes stipulated by external providers, such as grant providers or bondholders, as well as amounts that are restricted constitutionally or through legislation. Committed fund balance includes amounts that can be used only for the specific purposes that are determined by a formal action of the government's highest level of decision-making authority. Assigned fund balance applies to amounts that are intended for specific purposes as expressed by governing body or authorized official and applies to remaining resources in any governmental fund other than the general fund. Unassigned fund balances include all amounts not contained in other classifications for the general fund and deficit fund balances in any other governmental fund.